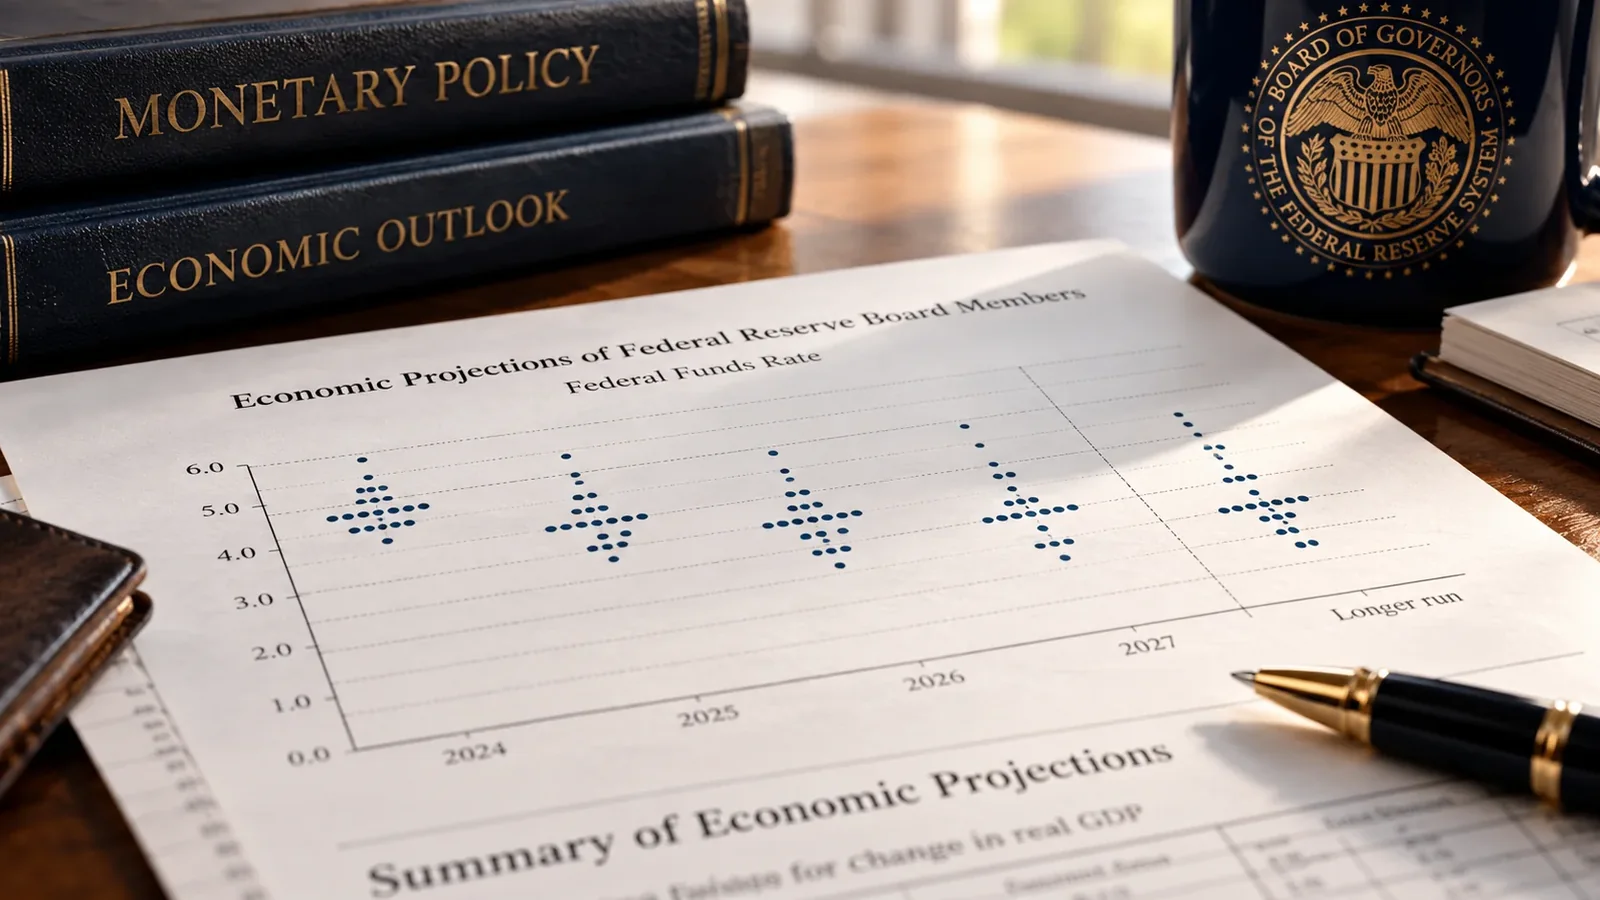
In a historical example from June and September 2026, the Federal Reserve’s median projection for the federal funds rate at the end of 2027 rose from 3.6% to 4.1%.
That was a noticeable change in policymakers’ interest-rate outlook. Yet the figures weren’t a new rate decision, and they didn’t represent a policy path agreed upon by the entire Federal Open Market Committee.
They came from a chart filled with small dots.
What do those dots reveal about the Fed’s thinking, and what should traders make of them?
What Is the Fed Dot Plot?
The Fed dot plot shows individual Federal Open Market Committee (FOMC) participants’ assessments of where the federal funds rate should be at specified points in the future, based on their economic outlooks and judgments about appropriate monetary policy.
Each dot represents one participant’s assessment. The chart covers the end of the current year, several subsequent years, and the longer run. The dots are anonymous, so readers cannot identify which participant submitted a particular projection.
The chart forms part of the Summary of Economic Projections (SEP), normally published four times a year. Alongside the interest-rate assessments, the SEP presents projections for economic growth, unemployment, and inflation.
The dot plot therefore provides more than a single projected interest rate. It lets readers see how participants’ assessments are distributed, where they broadly align, and where their views differ.
How to Read the Fed Dot Plot
At first glance, the chart can appear confusing. Dots are scattered across different interest-rate levels and projected years, sometimes clustered closely together and sometimes spread widely apart.
Start with the horizontal axis, which identifies the projected years and the longer-run period. The vertical axis shows the federal funds rate as a percentage. For example, a dot at 3.625% under 2027 indicates that one participant considers a target-range midpoint of approximately 3.6% appropriate at the end of that year.
When multiple participants submit the same rate assessment, their dots appear alongside one another at that level. A cluster indicates several participants have similar assessments, while a wider vertical spread reveals greater differences in their projected rates.
Financial headlines usually concentrate on the median, the middle value when participants’ projections are arranged from lowest to highest. With an even number of projections, the median is the average of the two middle values.
The median provides a convenient reference, but it doesn’t tell the whole story. Two dot plots can have identical medians while showing very different distributions. In one, participants may cluster around the middle; in another, their assessments may be much further apart.
The longer-run column also has a different meaning from the dated projections. It represents participants’ assessments of where the federal funds rate would be expected to settle over time under appropriate policy and without further economic shocks. It is not a target scheduled for a particular year.
Understanding the dots, their distribution, and the median makes it possible to compare different SEP releases without relying solely on the headline figure.
Explore the Fed dot plot
Compare policymakers’ individual rate assessments from June and September 2026.
June 17, 2026
September 16, 2026
Historical FOMC participant assessments, not forecasts or commitments. Rates are target-range midpoints (or target levels). Dots are anonymous; you cannot track a participant across meetings. Dashed lines mark medians calculated from the plotted dots. The Fed rounds these medians to one decimal place in its published summary table. Source: June 2026 SEP, Figure 2 and September 2026 SEP, Figure 2.
What the Other Economic Projections Reveal
The SEP also shows what policymakers expect for economic growth, unemployment, and inflation. These projections help provide economic context for their assessments of appropriate interest rates.
Four measures appear in the economic projection tables:
- Real GDP growth: Expected economic growth after adjusting for inflation.
- Unemployment rate: The projected unemployment rate in the final quarter of each year.
- PCE inflation: Expected inflation measured by the Personal Consumption Expenditures price index, the measure underlying the Fed's 2% inflation objective.
- Core PCE inflation: PCE inflation excluding food and energy, which helps policymakers assess underlying price pressures.
These figures become more useful when examined together.
Suppose the median projected federal funds rate rises between SEP releases. The accompanying projections may show that policymakers expect inflation to remain elevated, economic growth to be stronger, or unemployment to be lower than previously anticipated. Those changes can help explain why higher interest rates are considered appropriate.
However, the SEP is not one unified forecast. Each participant submits projections based on their own economic assessment and preferred policy path. The published medians for different variables may therefore come from different participants.
Reading the economic projections alongside the dot plot provides useful context, but the median figures should not be treated as a single policymaker's complete forecast.
What Changes Between Dot Plots Can Tell You
A single dot plot provides a snapshot of policymakers' assessments. Comparing two releases shows how those assessments have evolved.
Consider the June and September 2026 projections. In September, the published median projected federal funds rate was higher for each comparable year-end period: 2026 rose from 3.8% to 4.1%, 2027 from 3.6% to 4.1%, and 2028 from 3.4% to 3.9%. The longer-run median rose from 3.1% to 3.2%.
But the distribution carries information the medians cannot. For the end of 2027, eight participants in September projected a federal funds target-range midpoint of 4.375%, compared with one participant at that level in June. The explorer above allows readers to inspect that shift directly.
The accompanying economic projections provide additional context. Between June and September, the median unemployment projection for 2027 declined from 4.3% to 4.1%, while projected real GDP growth increased from 2.3% to 2.4%. Median PCE inflation for 2027 remained at 2.3%.
Taken together, the September projections showed a somewhat stronger economic and employment outlook alongside higher assessments of appropriate interest rates. They do not establish precisely why individual participants changed their projections.
The anonymous dots also prevent us from identifying who moved their assessment or how much any specific person's view changed. These are comparisons between distributions, not individual voting records.
What the Dot Plot Cannot Tell Traders
The dot plot offers a valuable view of policymakers' thinking, but it cannot tell traders exactly where interest rates will be in the future.
Each dot represents an assessment of appropriate policy under a particular economic outlook, not a promise. Unexpected changes in inflation, employment, growth, or financial conditions can lead policymakers to revise their projections.
The median is similarly limited. It is a statistical summary of individual assessments, not a policy path approved by the FOMC.
Differences among policymakers should not be confused with uncertainty about the future. Participants might submit similar projections while recognizing considerable risks around their economic forecasts. The SEP includes separate information about forecast uncertainty and risks that the dot distribution alone cannot capture.
The distinction between Fed projections and market expectations matters as well. The dots show policymakers' assessments of appropriate rates, while futures markets reflect how market participants price possible outcomes. Those views can differ.
A higher median projection therefore doesn't automatically mean Treasury yields will rise or stocks will fall. Investors may already have anticipated the change, and other information released at the same meeting can influence market prices.
The value of the dot plot lies in understanding how policymakers currently assess the appropriate path of interest rates, how widely their views differ, and how those assessments change over time.